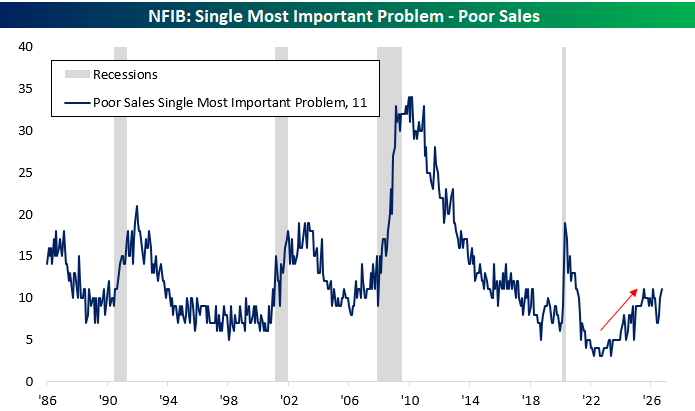
Bespoke Investment Group spotted something it did not like in the most recent National Federation of Independent Business survey this week: That small businesses increasingly report their “number one problem” is poor sales. Of all the options in the survey, “the one problem that you don’t want to be your #1 problem is poor sales,” the asset manager says. “During prior economic contractions, we’ve seen this reading for poor sales tick sharply higher. As shown below, while still relatively low for now, it has begun to tick higher again recently.”
The NFIB index fell to 97.9 in September, from 98.7 in August. “The other major business surveys also generally suggest that activity lost a little momentum towards the end of Q3, likely weighed down by the rebound in global energy prices,” according to Samuel Tombs and Oliver Allen at Pantheon Macroeconomics. (They also note that only 411 companies responded to the survey, down from a level of around 1,200 over a decade ago.)
Jobs growth is “essentially zero” outside healthcare
Mark Zandi at Moody’s Analytics thinks the U.S. economy is “vulnerable.” He is especially worried about the labor market: “Monthly payroll growth has averaged around 40,000 over the past year and has been essentially zero when excluding the healthcare sector. Hiring is moribund, hours worked are very low, and while the unemployment rate remains low, that is partly a reflection of declining labor force participation [from increased retirements and low immigration,]” he told Goldman Sachs’ Allison Nathan recently.
In addition, he’s concerned that higher rates being demanded by the Fed and the bond market could derail AI capex spending. “AI capex is also vulnerable as a higher cost of capital makes investment more expensive and falling valuations make it harder to raise the capital necessary to sustain the current pace of the AI buildout,” he says. “If rates remain at these levels or higher for longer than a quarter or two, AI could become the part of the economy that breaks.”
Inflation is out of control: “Two wars need to end before we get any relief”
That scenario—interest rates higher for longer—appears to be shaping up. The consumer price index for September came in at 3.7%, up from 3.4% the previous month and ahead of analysts’ expectations. The Fed may feel compelled to act by raising rates further.
“Inflation is cooking with gas,” Jamie Cox of the Harris Financial Group told Fortune in an email. “It is abundantly clear where the inflation impulse originates, but two wars need to end before we get any relief. The Federal Reserve made the mistake of calling Covid-era inflation transitory, and now it appears they are set to make the same mistake in reverse on the energy supply shock.”
Pimco’s Tiffany Wilding was equally alarmed: “This is not a good data point for the Federal Reserve, whose committee members had been signaling they were not likely to raise interest rates later this month. After the [CPI] report was published, markets priced in a 50 percent chance that the central bank would raise rates again in October.”
Global wave of selling as traders flee tech stocks
Traders decided they hate tech stocks in the last 24 hours, driving a global wave of selling. The tech-heavy South Korean KOSPI index fell 8% and at one point triggered a halt in trading. Nasdaq futures were down 1.03% this morning, signalling that the bloodletting may continue after the markets open in New York. CoreWeave lost 15.46% yesterday and sank a further 5.89% overnight; Oracle was down 8.83%, and lost another 1.57% in post-market trading. Chipmakers suffered declines across the board.
Counterintuitively, much of the selling came despite some good news for the sector: Chipmaker TSMC reported Q3 earnings today that beat expectations and guided that its capex would increase over the next two years. In addition, Apple stock closed at a new record high, making it only the second company (after Nvidia) to gain a $5 trillion market cap. And Anthropic reported that it was profitable (on an adjusted basis) although its revenue growth ($17 billion in Q3) appears to be slower than previously estimated
The drama extended to the bond market, where investors couldn’t decide whether the benchmark 10-year U.S. Treasury was a safe haven or offering a risk premium. The yield on the bond peaked at 5.32% before sinking back to 5.08% this morning—a huge swing for the normally sedate asset.
- S&P 500 futures were down 0.24% this morning. The index was down 1.11% yesterday.
- In Europe, the Stoxx 600 was down 0.10% in early trading, and the U.K.’s FTSE 100 was up 0.48% before lunch.
- Asia: South Korea’s KOSPI was down 7.57%. Japan’s Nikkei 225 was down 4.90%. India’s Nifty 50 was up 1.68%. China’s CSI 300 was down 1.23%.
- Brent crude was $106 per barrel.
- Bitcoin fell to $81,265.
This story was originally featured on Fortune.com